Tag Archives: economy

The beginning of the End

The College Woods neighborhood in Riverside, Edmonton is made up of 115 homes built mainly between 2002 and 2004.  The neighbourhood was largley completed and occupied by 2005.

However, six lots or so were sold to independent builders and those houses were constructed from 2005 up to around 2014 with the exception of one lot which remained empty.

New Neighbour’s are coming

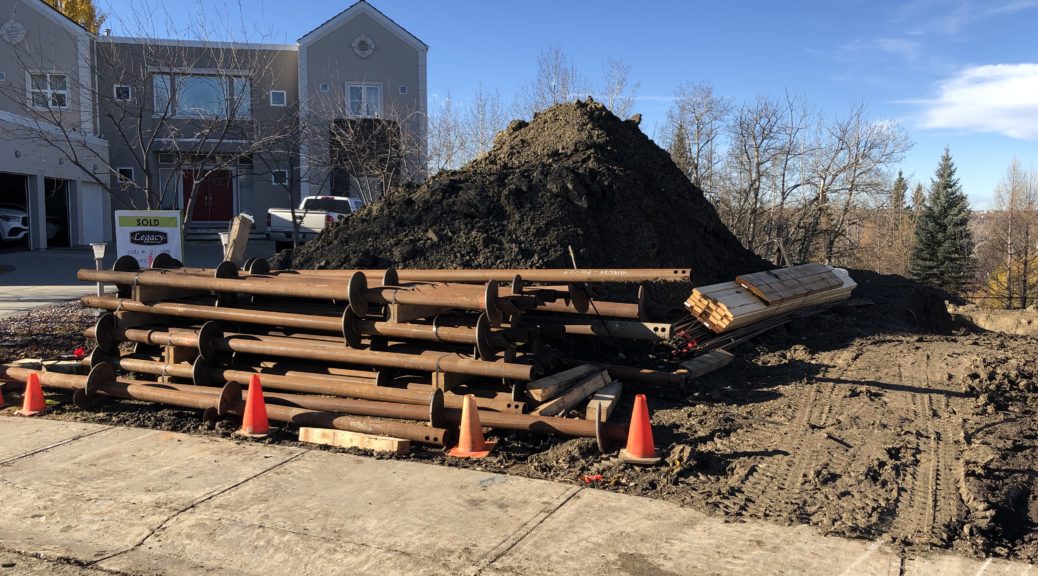
The empty lot was three doors south of our current home. Finally, I guess property values reached an acceptable point for the purchaser and the lot sold and building commenced.

Looks like our neighbourhood will, after 19 years, be completly built out.  This does seem to me to be a long time for an empty lot to sit and I am bit surprised the city did not encourage the owner to build, for the increased tax revenue.

Canadian Housing Markets Reasonable

There has been a lot in the news lately about the hot housing markets in Canada although given the large amount of available land in Edmonton, to mention nothing of Northern location, itis not really a hot spot.

We have noticed, as a personal anecdote, that houses in surrounding area that were sitting on the market for years suddenly sold this summer and our neighbours listed and sold their home within three months.

Pandemic Economy Impacts

Probably  the Spector of rising interest rates and higher inflation is at least one of the factors driving this behaviour, thus it is country wide albeit at different paces depending on geographic location.

For us this is the end of a era, that is an incomplete neighbourhood , but also this is likely a sign of the current economic state.  I wonder what is next.
Low Interest

Considering the basic principle of supply and demand, lack of interest is indicative of low demand.  Not wanting to know or learn more about something or someone (i.e., paying attention or focus) leads to disinterest.

In financial terms interest is money paid regularly at a particular rate for the use of money lent.  Your indebtedness creates interest both that which you have pay (financial) and attention (focus).

That is to say the debt has your focus, it worries you and requires attention.   This leads to a focus or interest in the rate of interest. Low rates (and high rates) can grab your attention.

Financial Interest Rates

In an interesting twist of the word, for me anyway,  low interest rates in fact have a high demand, people are interested in them .  I would be far more interested in borrowing at a low rate than a high one.

Our current financial interest rate environment is historically low and has been for some time.  This situation has become more of a norm than anything else.

High Rates

In the 1980’s, when we bought our first home interest mortgage rates were around 20% compared with less than 3% today, in some cases .

We survived through high and low interest ups and downs but over the last 20 years low rates have been the norm and interest in having a loan has been high.

These has resulted in the current world wide economic dilemma.   Economies and employment rates are typical of those associated with high interest rates but Governments fear raising them will cause a debt implosion, which it well might.

Where does all the money go?

The last couple of weeks the media have been on a glorified dance of doom and gloom about the economy.  This is a message that catches attention and so is step number one to a good story which leads to readership and associated revenue (whatever the revenue model is).

Some will argue the media goal is to share information objectively to keep the public informed, and while in some cases that might be true I believe profit is still an underlying objective (cynical me).

Economic Downturn Impacts

Investing to drive economic growth comes in a variety of flavors. Simplistically there are two classifications for investments:

– low risk investments which typically have a define fixed rate of return (fixed income) and often are “guaranteed”.  These are typically things like Corporate Bonds, Government Bonds, Guaranteed Investment Certificates, Bank Accounts.

– higher risk which usually are intended to achieve a greater return could result in not only no return but even loss of the original investment.  The most common of these is equity type investment and can include stocks, funds, options, commodities.

High Risk Investments and the Economy

At the summary level, monetary investment is a key way to drive economic growth.   Money is invested to enable more production (whether a physical product or service).

The increased production leads to increased profit which is returned to the investor.  Basically this is a key goal of investing.

As time goes by, if revenue and profit in the target investment continue, the return on investment continues.

So what happens when money is invested and production does not continue to increase or even worse declines?

Where does the money go?

Usually the low risk investments are not effected, it would require a long, deep and traumatic downturn like the world wide depression of the 1930’s to impact them.  This is not the case for the higher risk types.

For equity investments, when the economy climbs the monetary value of the investment rises and when the return drys up the monetary value of the investments drops.   So when the economy is in a downturn, profits drop or even worse turn to loses and so does the investment value.

Since the increase in the equity of the investment is based on demand the higher value just appeared – that is more money was not printed nor did the investment itself change so the increased amount of money someone would pay for your investment is just perceived worth.

The same is applies for the underlying income supporting the investment (for example the profit the company you invested in dried up).  The profit just disappeared, but the amount of money in the economy did not really change.

So in the economic downturn the monetary value of the investment disappears, but since it never really existed in the first place – did it really?

The answer to where does the money go is simply, it never existed in the first place so it did not need to go anywhere.

Disclaimer – This is a very complex topic for which only some basic concepts are commented on here, in future posts I will continue to build and explore this topic.

Supply and Demand

Continuing to explore the theme I started yesterday,  about why we pay what we do for things, today we’ll explore the concept of supply and demand and how it affects what things are worth.

My example of a pub lunch that cost $4.00 in 1977 and $15.00 raised the question of why I would be willing to pay so much more some 38 years later, for basically the same thing.  Part of the answer is I could afford it easily.

Another part of the price equation is demand. For the pub owner the more people that want to buy the lunch the more likely he (or she) is to raise the price.  It’s pretty intuitive that demand is linked to price however it really is a complex relationship and demand is driven by far more than just price.


Lets Consider Desire (Demand) and Availability (Supply)

In fact if the purchaser has more  funds (e.g., through inflation) they can afford to pay more.  In this case it is possible desire for the product is driving the purchase decision as opposed to cost.  (Think, ” I want it”).   Additionally, as we know, affordability can be enhanced by borrowing, in these cases the purchase ultimately costs more (the interest on the loan) but we get it now and satisfy our desire.  Clearly cost was not the prime factor in the decision.

Desire is also linked to availability.  “It’s the last one I better snap it up regardless of price”  or “There are ton’s of those on the market, no hurry to buy, let’s wait the price will probably go down”

A key to successful product marketing is to raise desire.  That is help you understand the reasons you need a thing – a low price can be one of these reasons.  In conjunction with desire it helps to give impression of urgency (hurry before they are gone).

The underpinning of the purchase though is definitely affordability.  This is why things can cost more, because not only did the price go up but incomes rose as well so we can afford it (inflation affects both cost and revenue).

How about branding?

A product’s brand is just a label for what people think about the product.  That is things like reliability, value, quality.   Consider two automobiles – a Ford and a BMW.  Both are just molded tin on wheels that take you places – basically perform the same function but the brands have very different impressions and these contribute to demand (also the availability of the product from the automakers) and thus drives the price.

What’s Next?

Tomorrow’s  post will continue on this theme focusing on the impacts of deflation and recessions on the pricing, supply and demand.

How much is something worth

Out of curiosity the other day I decided to check the purchasing power of my annual income of my first job (in the 1970’s) with today.  My starting salary for a management training role for a university graduate was $9,800.   According to the purchasing power calculator at “buyupside” this would be about $41,000 in 2014 dollars.

A check of “payscale.com” shows a starting level income of $34,000 to $48,000  for a newly graduated BSc ( IT roles) .   The range quoted is based on 4 different role types.  (I have excluded Sr level and Mgmt roles and considered only the lowest end of the salary range for the other roles).

So, my first job’s measly $9,800 a year was right in the range of what a new BSc. might get in today’s dollars.  This is not an exact comparison as my first job was in Financial services not IT but it gives an indication of how things line up from 40 years ago to today, in terms of what things are worth.

This is just one example, but for me anyway the purchasing power of my annual income in my first job out of university maps to that of someone today with a similar degree.

So how is the worth of things determined.  I mean when I started work I bought my lunch at the pub next door to the bank branch where I worked for under $4.00 a day (including the beer).  Today an equivalent lunch (including the beer) would be $15.00.   Similar food and beer, very different assigned worth.  That is to say I am willing to pay $15 for the same thing I paid $4.00 for only yesterday (well 40 years ago but who is counting).

Why am I willing to pay the higher amount?  The most simple answer is because I can.  This is what purchasing power is about.   I have easily enough money to buy the lunch at today’s rate as I did back 40 years ago because I am paid so much more in today’s dollars.  This as we all know is inflation.

Whats the Point?

Fair question.  Today’s post is really just background for a series on the value of things, inflation, deflation and other economic calamities.

Check in  tomorrow more thoughts on these topics and deeper exploration of what the impact of changing buy power is.